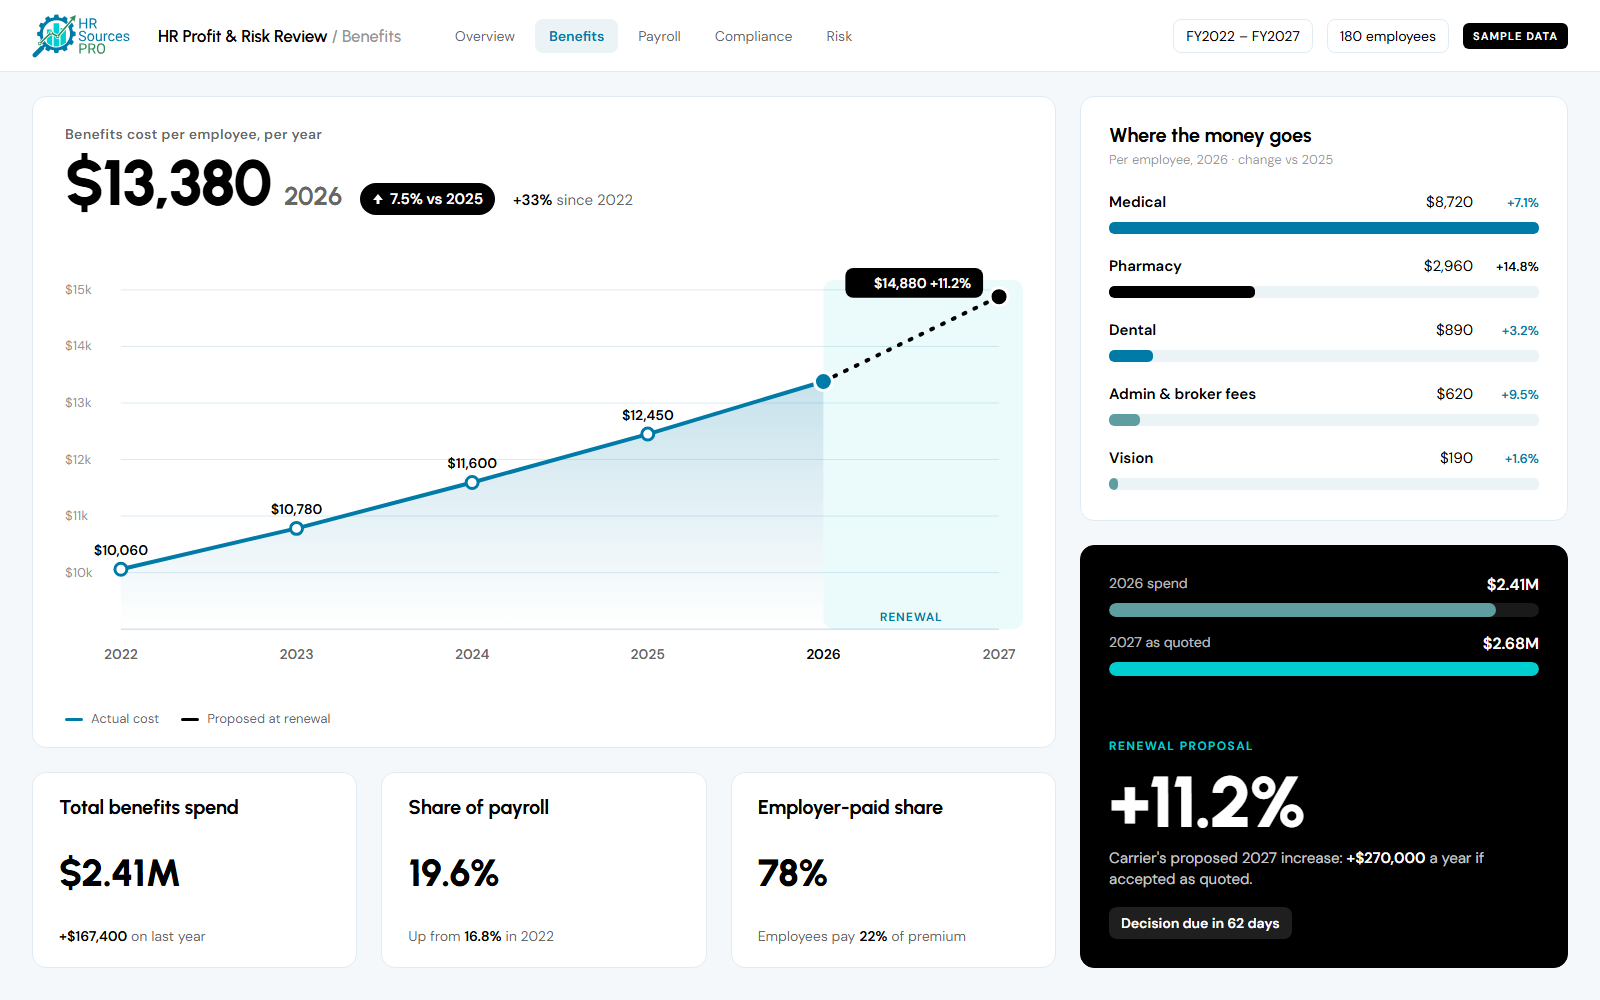
A free review of your benefits, payroll, compliance and HR operations. No cost, no obligation, no broker conflict.
Led by Lianne Rubbo, CHRO, 25+ years.
See what the review coversHow it works
No charge, no call to sit through, and nothing to qualify for. You send what you already have; Lianne does the rest.
No charge, no call, no qualifying.
Send your payroll register, census and invoices.
Of what you spend now, and how your operation runs.
On your behalf, from your side of the table.
And walk you through what we found and what we recommend.
Read by Lianne Rubbo herself, back to you in 1 to 3 business days.
About Lianne
Someone whose only job here is your company and the people in it.
Let’s connect on LinkedIn“We have never completed an HR Profit & Risk Review without finding recoverable profit.”
Lianne Rubbo · CHRO / Director of HR Services · HR Sources Pro
A broker’s job is to place coverage. They know the carriers, they know the products, and they are paid when you buy. That is a real skill, and it is not the same skill as knowing what a plan will do to your company.
Lianne has run HR at scale. She reads a benefits package the way your people will actually experience it: what it does to hiring, to who stays, to the person reconciling payroll every month, and to your exposure when something goes wrong. She knows which lines are negotiable and which are theatre.
So she reads what is on the table, takes it to market, brings the bids back to you, and works the process from your side of it. Not selling you something. Sitting with you while you decide. And when the decision is made, she can stay for the implementation if you want her to.
We are not paid on your premium. We have saved companies millions on benefits, and the measure of this is not what you buy. It is whether the business runs better afterwards, and whether your people feel it.
We could charge for the Review. We don't.
This is the area of your business that costs the most and gets examined the least, and it is the fastest way to show you what we are actually like to work with. You get the findings, the numbers and the recommendation either way, with nothing owed.
If what we find is worth acting on, most companies want help acting on it - the implementation, and then someone senior in the chair afterwards. That is the work we are interested in: Lianne as your Executive HR consultant, on a defined engagement block, through the rollout and beyond it.
We would rather earn that by doing the work in front of you than by pitching it.
First-year savings on her most recent Review
Days from decision to fully implemented
Years running HR and operations
In broker fees
What we examine
What you pay, what you actually receive for it, how much your employees carry, and what the same coverage costs elsewhere. Usually where the money is.
Where the risk actually sits, what leaks to the carrier, and whether the structure is the reason your renewal looks the way it does.
How it runs, what it costs, and how many hours a month it quietly consumes.
Whether your class codes and rates are correct, and whether claims are being managed or simply filed.
ACA, COBRA, wage and hour, handbooks, required training. Expensive in a way that stays invisible until it is not.
Whether a new hire’s first day runs itself, or costs three people a morning.
What you get back
What you are spending today, and what you could be spending instead. No jargon, and nothing you need a benefits background to read.
Alongside it, a conversation about how the work actually gets done in your company: where the manual effort sits, where the exposure is, and what we would change.
Where the money leaks
At firms with 10 to 199 workers, the employer’s family premium runs $1,226 below what large firms pay. The employee’s share of it runs $2,662 above. The cost did not disappear. It moved.
Annual worker contribution, 2025
+$2,662 a year, per enrolled employee
Average single deductible, 2025
57.5% higher
of your covered workers pay more than half the family premium
At firms of 200+, it is 5%. A 5.8× gap.
exposure per concluded wage-and-hour action
Up 78% since FY2020, while the number of investigations fell 35%.
benefit cost growth in 2026, against 3.1% for wages
The first year benefits outpaced wages. The line already being shifted is the one growing fastest.
To be straight about it: mid-market employers are not stingy. They are more likely than large firms to cover the entire single premium - 29% do, against 7% at firms of 200+. The failure is specific to family coverage, and it is mostly invisible from the inside: 21% of these employers believe their people have no affordability concern at all.
Family contribution, deductible, share paying over half, single-premium coverage, affordability belief: KFF, 2025 Employer Health Benefits Survey (27th annual, data year 2025). Wage-and-hour exposure: US DOL Wage and Hour Division, Enforcement Statistics: All Acts, FY2013–FY2025. Exposure per action is back wages plus civil money penalties divided by concluded actions (derived). Benefit and wage cost growth: US BLS Employment Cost Index, civilian workers, Q2 year-on-year, via FRED.
A free review of your benefits, payroll, compliance and HR operations. No cost, no obligation, no broker conflict.
Start my free reviewRead by Lianne Rubbo herself, back to you in 1 to 3 business days.